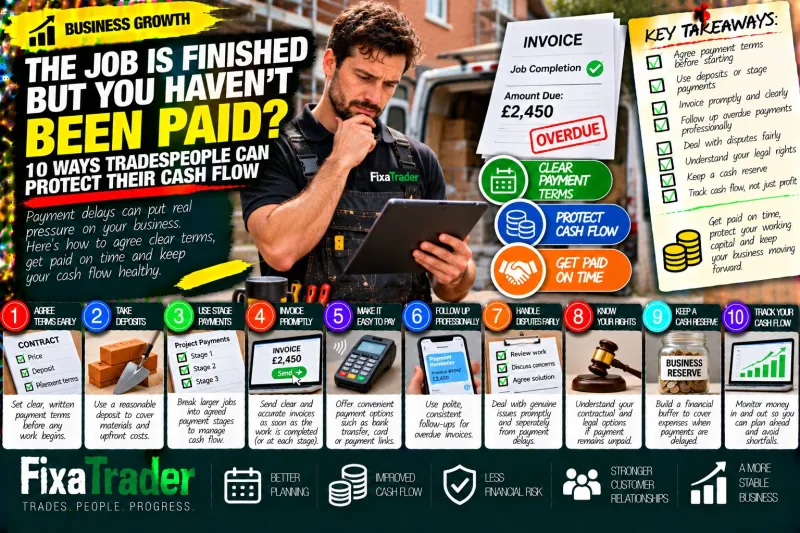
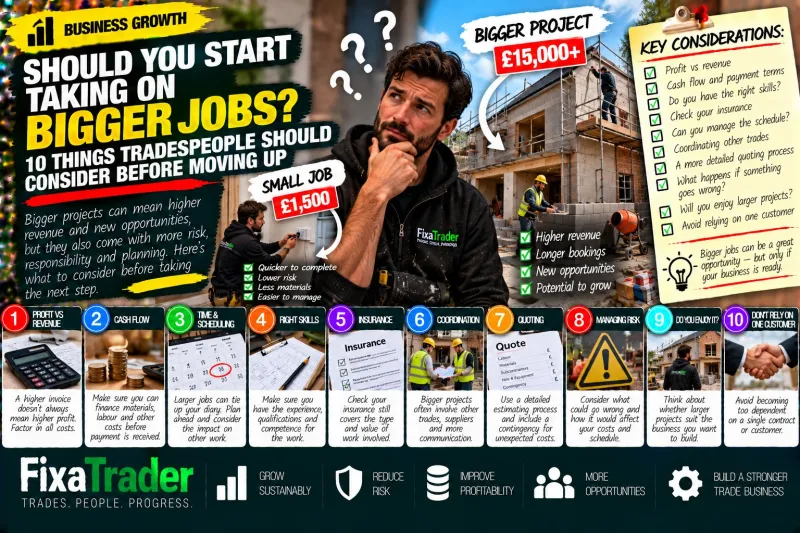
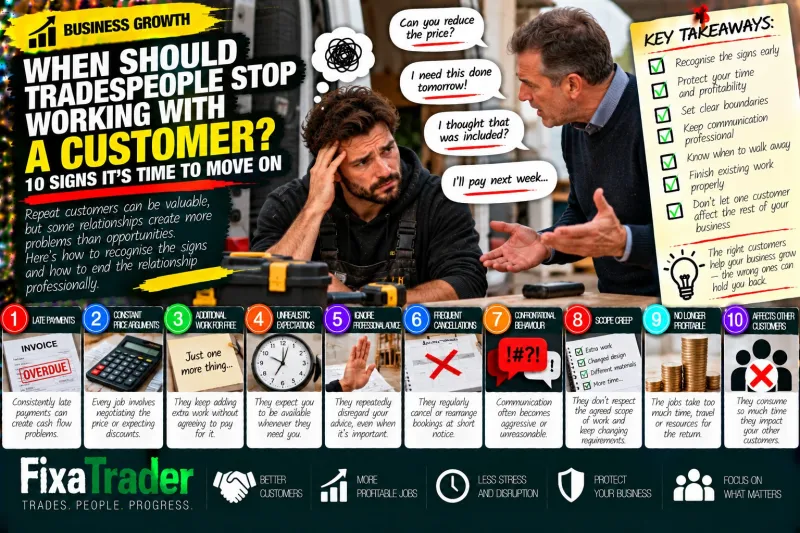
The Job Is Finished but You Haven't Been Paid: 10 Ways Tradespeople Can Protect Their Cash Flow
You've completed the installation. The customer has inspected the work, everything is functioning as expected and you've sent the final invoice. Now you're wait...
The customer has inspected the work, everything is functioning as expected and you've sent the final invoice.
Now you're waiting for payment.
Meanwhile, your supplier needs paying, your van insurance is due and you've already purchased materials for the next job.
On paper, the business has made a profit.
But the money hasn't arrived.
For self-employed tradespeople and small contracting businesses, this situation can create serious pressure.
You can have a full diary, strong demand and a healthy order book while still struggling to cover everyday expenses.
That's because profit and cash flow are not the same thing.
Profit measures the difference between revenue and costs over a period.
Cash flow concerns when money actually enters and leaves your business.
And timing matters.
Here are ten practical ways tradespeople can reduce payment problems, protect working capital and avoid allowing completed jobs to become unpaid debts.1. Agree Payment Terms Before Starting the Job
One of the simplest ways to reduce payment disputes is to establish when payment is due before any work begins.
Don't wait until the final invoice to introduce your expectations.
Your quotation or contract should explain the agreed price, what the customer is paying for and when payment becomes due.
For example, a small repair might be payable upon completion.
A larger renovation may involve a deposit and staged payments.
Commercial contracts may have different arrangements.
Your payment terms should make clear:
The total price or how it will be calculated.
Whether a deposit is required.
Any agreed payment milestones.
When the final balance becomes payable.
Which payment methods are accepted.
How variations and additional work will be charged.
For consumer customers, terms must be transparent and fair.
Avoid vague wording that leaves either party uncertain about their obligations.
A payment problem is much easier to prevent before the job starts than to resolve after the customer has received the finished work.2. Consider Deposits for Materials and Larger Projects
Deposits can help reduce the amount of money your business needs to commit before receiving payment.
This can be particularly important when purchasing expensive or specially ordered materials.
For example, imagine a project requires £2,500 in materials before installation can begin.
If you pay the entire amount yourself, your business carries that cash-flow burden until the customer pays.
An appropriately structured deposit can help.
However, deposits need to be reasonable and supported by clear terms.
You shouldn't assume that every deposit can automatically be retained if the customer cancels.
Consumer protection rules, the circumstances of cancellation and any actual losses may affect what can lawfully be kept.
Before requesting a deposit, consider:
The materials you need to purchase.
Whether products are bespoke or returnable.
The time before work begins.
The customer's contractual cancellation rights.
The amount of financial exposure involved.
A deposit should help manage genuine project costs, not function as an unfair penalty for changing plans.3. Use Stage Payments for Longer Jobs
On larger projects, waiting until everything is finished before receiving payment can create substantial financial pressure.
Stage payments can spread that risk.
For example, a renovation contract might provide for payments at clearly defined points during the project.
These could relate to completed phases of work rather than arbitrary dates.
The structure should reflect the nature of the job and be agreed in advance.
A good stage-payment arrangement should:
Identify what work triggers each payment.
Explain the amount due.
Be proportionate to progress.
Avoid ambiguity about completion.
Set out how changes will be handled.
For consumer projects, payment arrangements should remain fair and should not require customers to pay disproportionately ahead of work without appropriate justification.
Stage payments aren't suitable for every job.
But where projects run for several weeks or months, they can help avoid funding the entire installation from your own working capital.4. Send Invoices Promptly and Accurately
Sometimes late payment starts with late invoicing.
If you finish a job on Friday but don't send the invoice until the following Wednesday, you've already delayed the payment process.
Create a routine for issuing invoices promptly when payment becomes due.
Check that each invoice contains the necessary information.
For example:
Your business name and contact details.
A unique invoice number.
The customer's details.
A clear description of the work.
The relevant dates.
The amount payable.
VAT information where applicable.
The agreed payment due date.
Your payment details.
An accurate invoice reduces the chance of customers asking for clarification before paying.
For VAT-registered businesses, additional invoicing requirements may apply.
The easier an invoice is to understand and process, the fewer avoidable obstacles there are to getting paid.5. Make It Easy for Customers to Pay
Payment delays aren't always caused by customers deliberately withholding money.
Sometimes the payment process is unnecessarily complicated.
For example, a customer may need to find your bank details, confirm the invoice reference or arrange a transfer later.
Providing clear payment instructions can help.
Depending on your business, you might offer:
Bank transfer.
Card payments.
Secure payment links.
Other suitable electronic payment methods.
Each option has different processing costs and practical considerations.
Make sure customers know which methods are accepted before payment becomes due.
You should also take precautions against payment fraud.
If your bank details change, communicate this securely and encourage customers to verify unexpected changes.
Reducing friction at the payment stage can improve the customer experience and help money reach your business sooner.6. Follow Up Overdue Invoices Professionally
An overdue invoice shouldn't automatically lead to an aggressive message.
There may be a simple explanation.
The customer might have overlooked the invoice, misunderstood the due date or encountered a temporary problem.
Start with a polite reminder.
Identify the invoice, amount and original due date.
Ask whether there is anything preventing payment.
If the invoice remains unpaid, follow up in a structured way.
Keep records of communications.
A sensible process might involve:
Confirming the invoice was received.
Sending a reminder after the due date.
Asking whether any part of the invoice is disputed.
Requesting a specific payment date.
Escalating appropriately if the debt remains unresolved.
Avoid threats, harassment or misleading claims about legal consequences.
Consistent, professional follow-up is generally more effective than ignoring an overdue invoice until the situation becomes serious.7. Deal With Genuine Disputes Separately From Payment Delays
Sometimes customers withhold payment because they believe something is wrong with the work.
This requires a different response from a straightforward forgotten invoice.
Ask the customer to explain their concerns.
Review the agreed scope, completion records and any relevant photographs.
If necessary, arrange an appropriate inspection.
Under the Consumer Rights Act 2015, consumer services must generally be performed with reasonable care and skill.
Where statutory requirements haven't been met, the customer may have rights to repeat performance or a price reduction, depending on the circumstances.
However, a complaint doesn't automatically establish that every amount claimed by the contractor is invalid.
Equally, the contractor shouldn't dismiss a genuine defect simply because an invoice is outstanding.
Separate the question of whether the work is satisfactory from the question of which payments are properly due under the contract and applicable law.
Where the disagreement is significant, independent advice or dispute resolution may be appropriate.8. Understand Your Rights When Invoices Remain Unpaid
The legal position depends partly on whether your customer is a business or a consumer.
For qualifying business-to-business debts, the Late Payment of Commercial Debts (Interest) Act 1998 may allow statutory interest and fixed compensation, subject to the applicable rules.
Statutory interest is generally calculated at 8 percentage points above the Bank of England base rate for qualifying commercial debts.
That regime doesn't apply in the same way to ordinary consumer debts.
You shouldn't automatically add commercial late-payment penalties to a homeowner's invoice.
Any contractual interest or late-payment charges must be legally enforceable and, for consumer contracts, fair and transparent.
For unresolved debts, options may include a formal letter before action, mediation or a court claim.
The appropriate procedure depends on the parties, amount and circumstances.
Construction contracts can also involve additional payment and adjudication rules, although important exclusions apply, including certain residential occupier contracts.
Before escalating an unpaid invoice, establish which legal rules apply to the particular customer and contract.9. Keep a Cash Reserve for Payment Delays
Even well-managed businesses experience payment delays.
A cash reserve can provide breathing room when invoices take longer than expected.
The appropriate amount depends on your operating costs, commitments and financial circumstances.
Start by identifying essential expenses.
These might include:
Vehicle finance, fuel and insurance.
Tools and equipment.
Business insurance.
Software subscriptions.
Premises costs.
Wages and subcontractor commitments.
Tax obligations.
Supplier payments.
Consider how long the business could operate if several expected payments were delayed.
A reserve doesn't need to be built overnight.
You might gradually set aside a proportion of receipts when cash flow allows.
The purpose of a cash reserve is to stop one late-paying customer from immediately disrupting the rest of your business.10. Track Cash Flow Rather Than Looking Only at Profit
A business can appear profitable while facing a shortage of available cash.
Imagine you've completed £15,000 worth of work this month.
But only £8,000 has been paid.
If your immediate expenses total £10,000, you may have a cash shortfall even though the remaining invoices are expected to be paid later.
This is why cash-flow forecasting matters.
You don't necessarily need complicated accounting software to begin.
A spreadsheet can help you track expected receipts and payments.
Useful information includes:
Current bank balance.
Outstanding invoices.
Expected payment dates.
Supplier bills.
Payroll commitments.
Upcoming tax payments.
Materials required for future jobs.
Other fixed operating expenses.
Update the forecast regularly.
And avoid treating an expected customer payment as guaranteed cash until it arrives.
Knowing what's likely to happen to your bank balance over the next few weeks can be more useful than simply knowing how much you've invoiced.What Should You Do When a Customer Says They'll Pay Next Week?
A promise to pay can be encouraging, but it doesn't automatically resolve the problem.
Ask for a clear payment date.
Confirm the arrangement in writing where appropriate.
If the customer is experiencing financial difficulty, you may consider a payment plan.
However, any arrangement should be realistic and documented.
For example, you might agree to payments on specified dates until the outstanding balance is cleared.
Be careful not to waive contractual rights unintentionally or make arrangements that conflict with applicable legal requirements.
If the customer repeatedly misses agreed dates, consider obtaining debt-recovery or legal advice.
A payment promise is most useful when it leads to a clear, realistic and documented arrangement.Should You Stop Work If a Customer Misses a Stage Payment?
This depends on the contract and the applicable legal rules.
Some agreements provide rights to suspend work following non-payment.
Certain qualifying construction contracts may also provide statutory rights relating to suspension.
However, these rules don't apply universally.
In particular, contracts involving residential occupiers can be treated differently.
Stopping work without a valid contractual or legal basis could expose your business to a claim for breach of contract.
Before suspending work, check the agreed terms and seek appropriate advice where necessary.
Don't assume that an overdue payment automatically gives you the right to abandon a project without notice.How Can You Spot Potential Payment Problems Before Starting?
No screening process can guarantee that every customer will pay on time.
But certain warning signs may justify further discussion.
For example:
The customer refuses to agree payment terms.
They repeatedly change the agreed scope without documenting changes.
They insist on unusually long payment periods without explanation.
They are unwilling to confirm who is responsible for payment.
They dispute ordinary contract terms before work begins.
They request substantial additional work without agreeing a price.
These behaviours don't necessarily mean a customer is dishonest.
However, they may indicate a higher risk of misunderstanding or disagreement.
For commercial customers, appropriate credit checks or references may be useful.
For homeowners, clear written agreements and proportionate payment schedules can help manage risk.
The goal is to identify uncertainty before it turns into an unpaid invoice.Should You Offer Discounts for Early Payment?
Some businesses consider offering a small discount to customers who pay promptly.
This may be useful in particular commercial arrangements.
However, discounts reduce your margin.
Before introducing one, calculate whether receiving the money sooner justifies the cost.
For example, a 2% discount on a £5,000 invoice reduces the amount received by £100.
That may or may not be worthwhile depending on your cash position and alternative financing costs.
Discount terms should be clear and agreed in advance.
For many smaller trade jobs, straightforward payment on completion may be simpler than introducing an early-payment incentive.
Don't sacrifice profitability to solve a cash-flow problem that could be addressed through clearer payment terms and better invoicing.What If a Customer Refuses to Pay Anything?
If a customer refuses payment entirely, avoid reacting emotionally.
Start by identifying the reason.
Is the amount disputed?
Does the customer allege defective work?
Are they experiencing financial difficulties?
Or are they simply refusing to engage?
Gather the relevant documentation, including the quotation, contract, invoices, photographs and correspondence.
Where appropriate, send a formal written demand that accurately sets out the debt and the basis on which payment is claimed.
For unresolved disputes, consider mediation, professional debt recovery or legal proceedings.
In England and Wales, the court procedure and applicable pre-action requirements depend on the circumstances.
Avoid removing installed materials, entering a property without permission or making threats as a means of recovering payment.
A documented, lawful recovery process is safer than taking matters into your own hands.Five Questions to Ask Before Starting Your Next Job
Before accepting a project, consider:
When will I be paid? Make sure the payment schedule is clear.
What will I need to spend first? Identify materials and other upfront costs.
Can I fund the work until payment arrives? Consider the effect on working capital.
What happens if the scope changes? Agree how additional work will be priced and authorised.
What happens if payment is delayed? Understand the contract and your lawful options.
These questions can help prevent cash-flow problems before they arise.The Bottom Line: A Profitable Job Only Helps When the Money Comes In
Winning work and completing projects are essential parts of running a trade business.
But getting paid is just as important.
Late payments can prevent you from purchasing materials, meeting financial commitments and taking on new opportunities.
The best protection starts before work begins.
Agree clear terms.
Use appropriate deposits and stage payments.
Invoice promptly.
Follow up consistently.
Keep records.
And monitor your cash position rather than relying solely on projected profit.
You won't be able to eliminate every late payment.
But you can build a business that's better prepared when they happen.
A successful trade business isn't simply one that completes profitable jobs. It's one that manages its money well enough to keep operating, investing and growing between payments.
0 Comments
No comments yet — be the first to share your thoughts.